How it works
From a pile of letters to one calm plan.
Add what you owe, in any of four languages. Hisab shows you what to pay first, writes to your bank for you, and tells you what your AECB report says about you. Free, on your phone, no account.
01
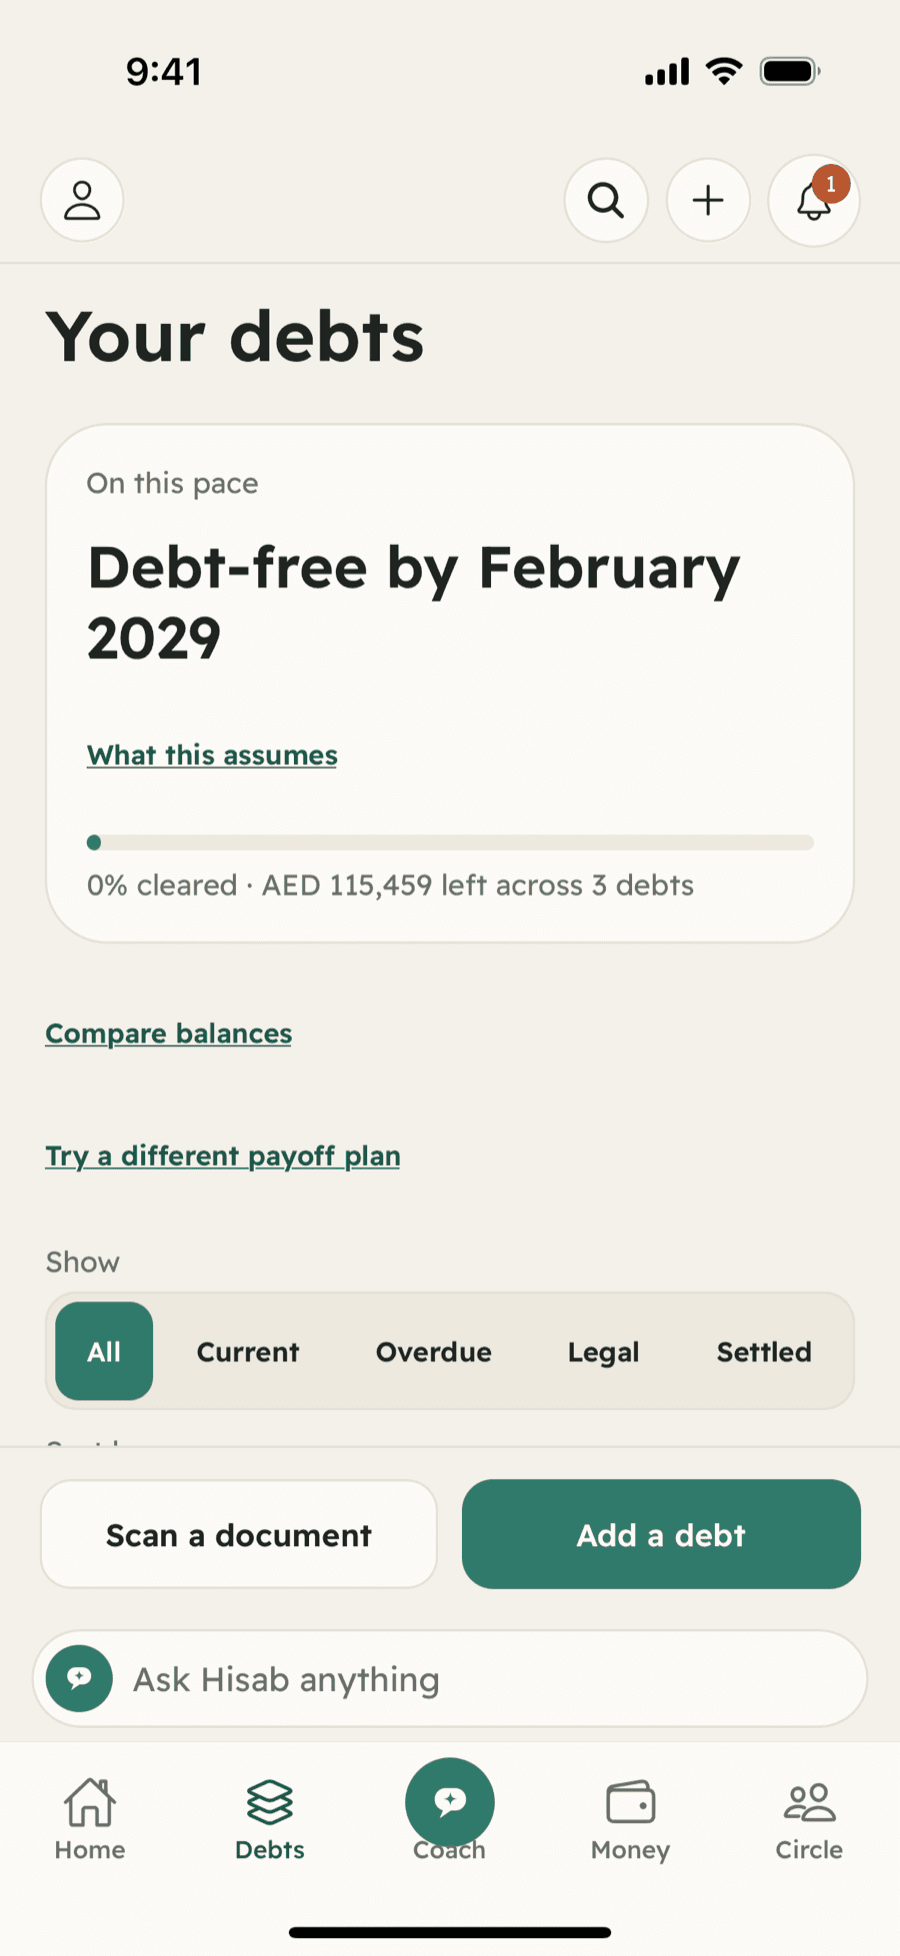
Every debt in one calm place.
Cards, loans, BNPL, rent, money owed to a friend. One running total, and one date you are working towards.
02
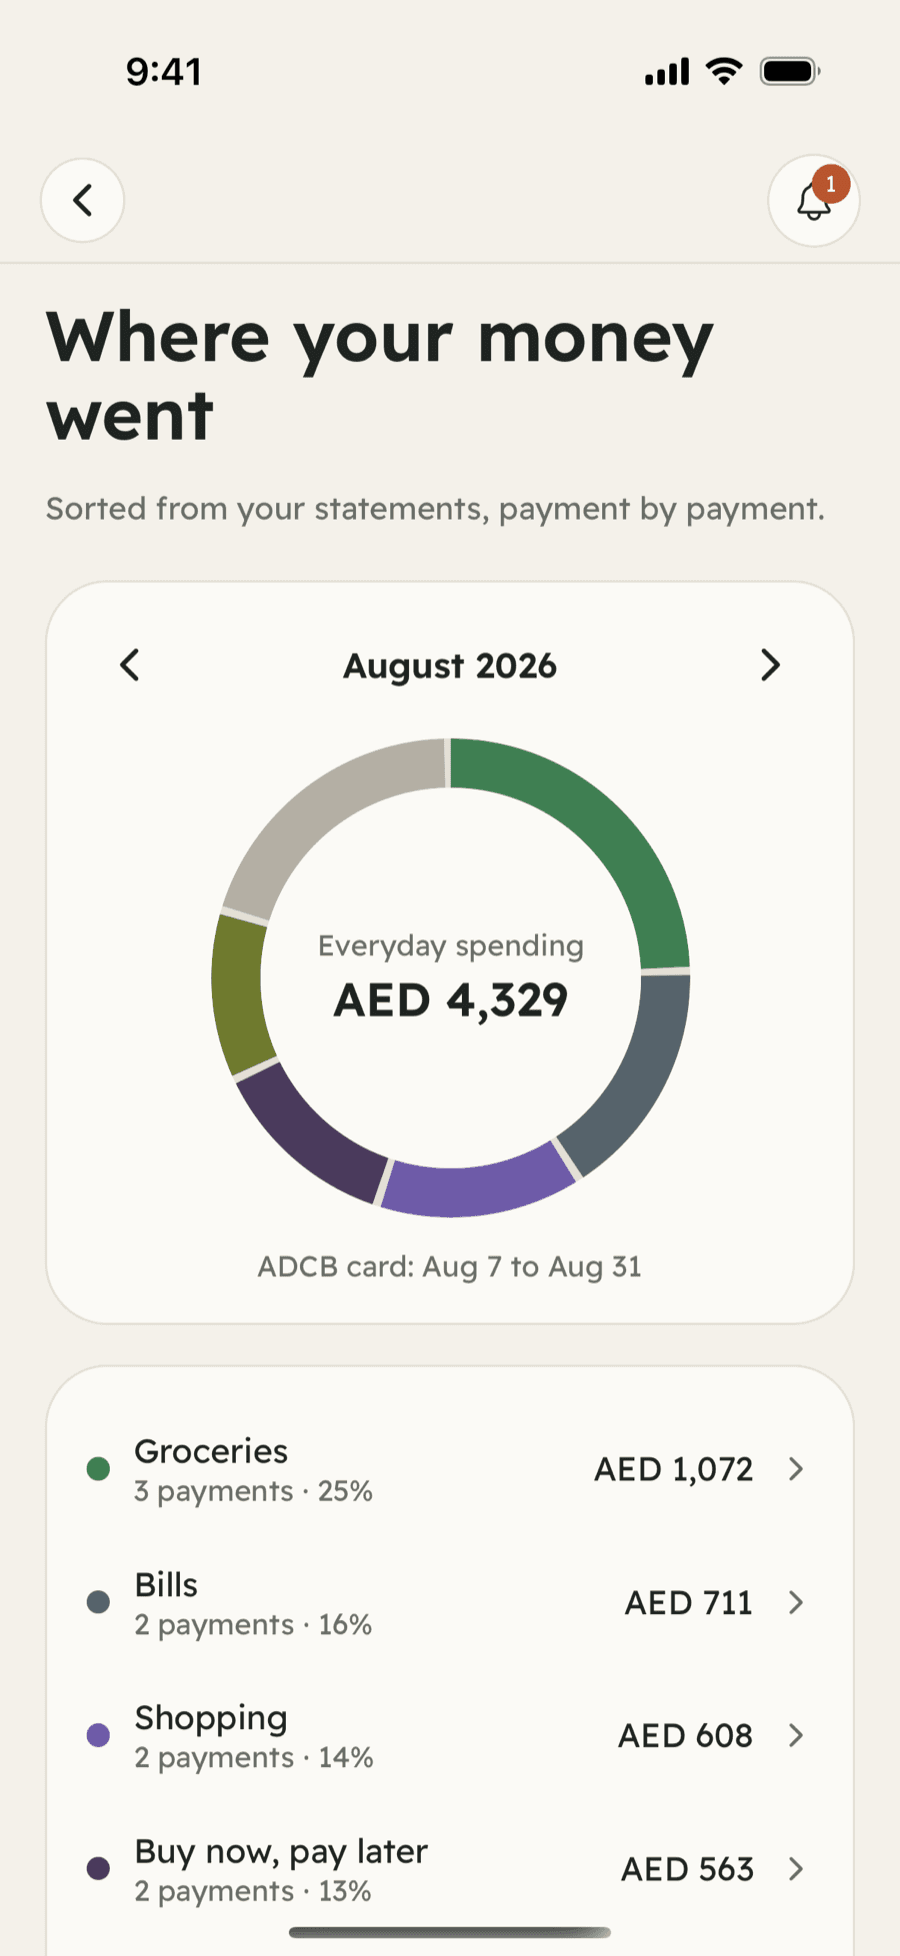
See where your money went.
Share a bank or card statement and Hisab sorts every payment into categories for you: groceries, delivery apps, bills, buy now pay later. No typing, and it stays on your phone.
03
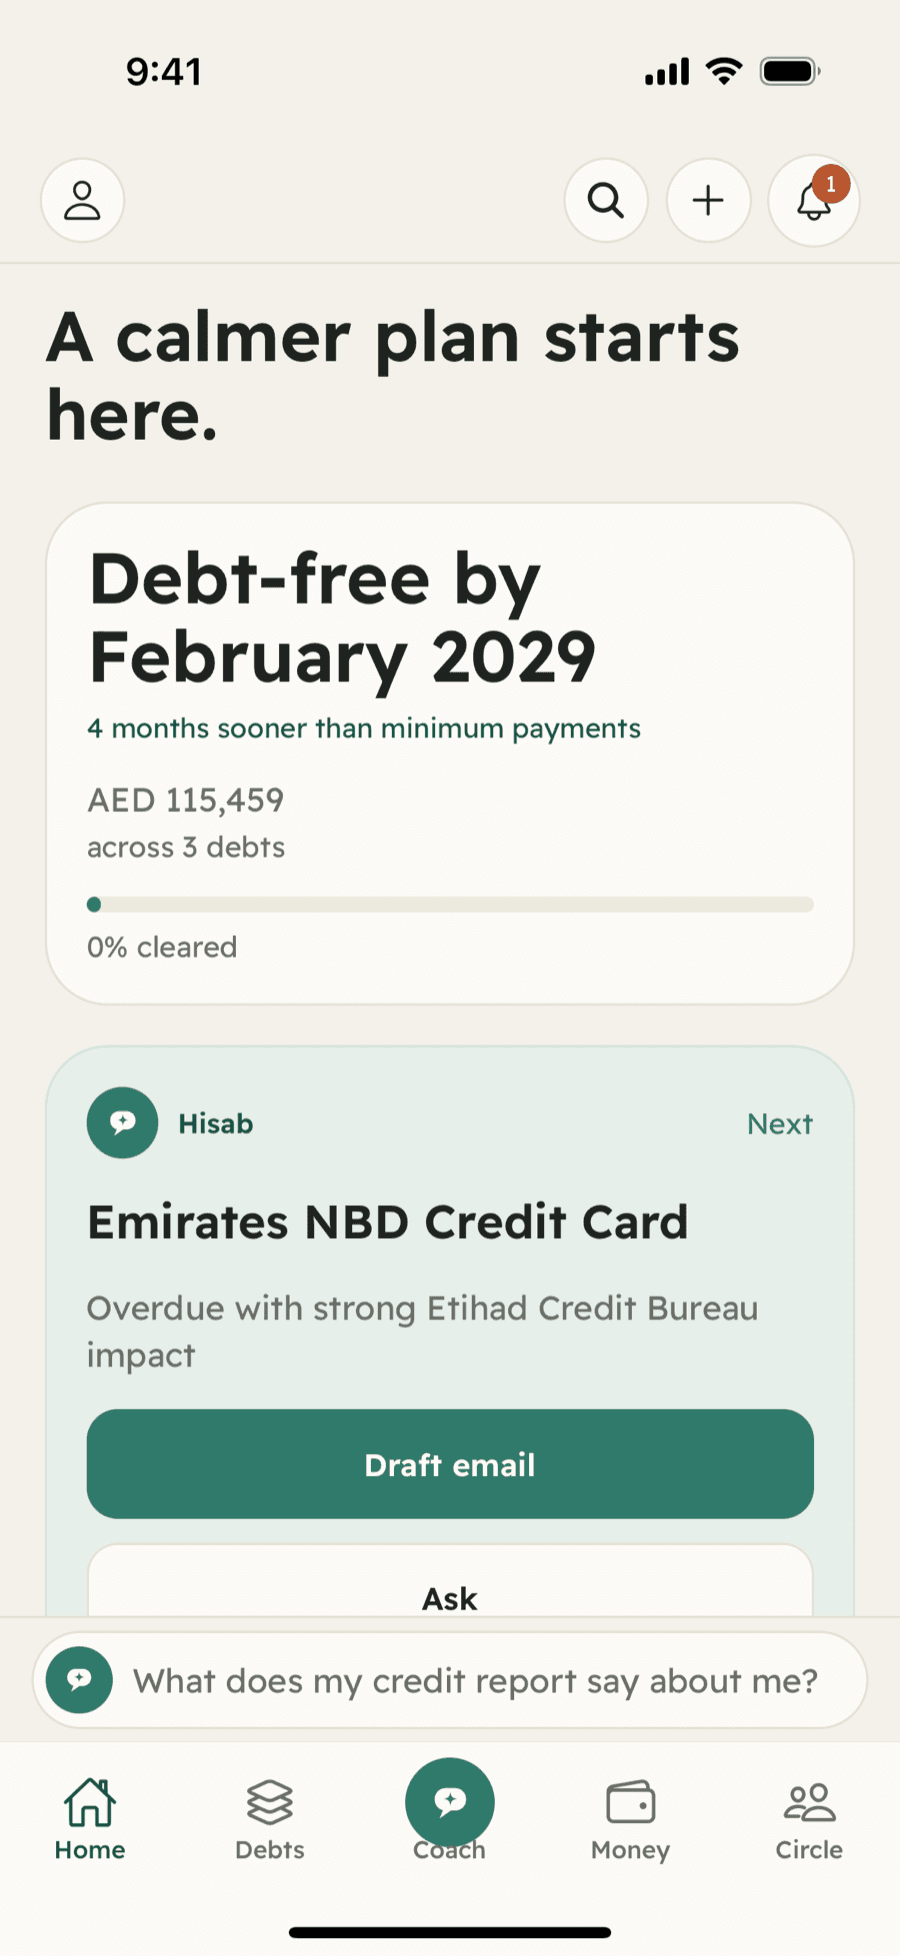
Know what to pay first, and why.
Hisab ranks by pressure, not by size: legal notices first, overdue next, then the highest interest. It gives you the reason every time.
04
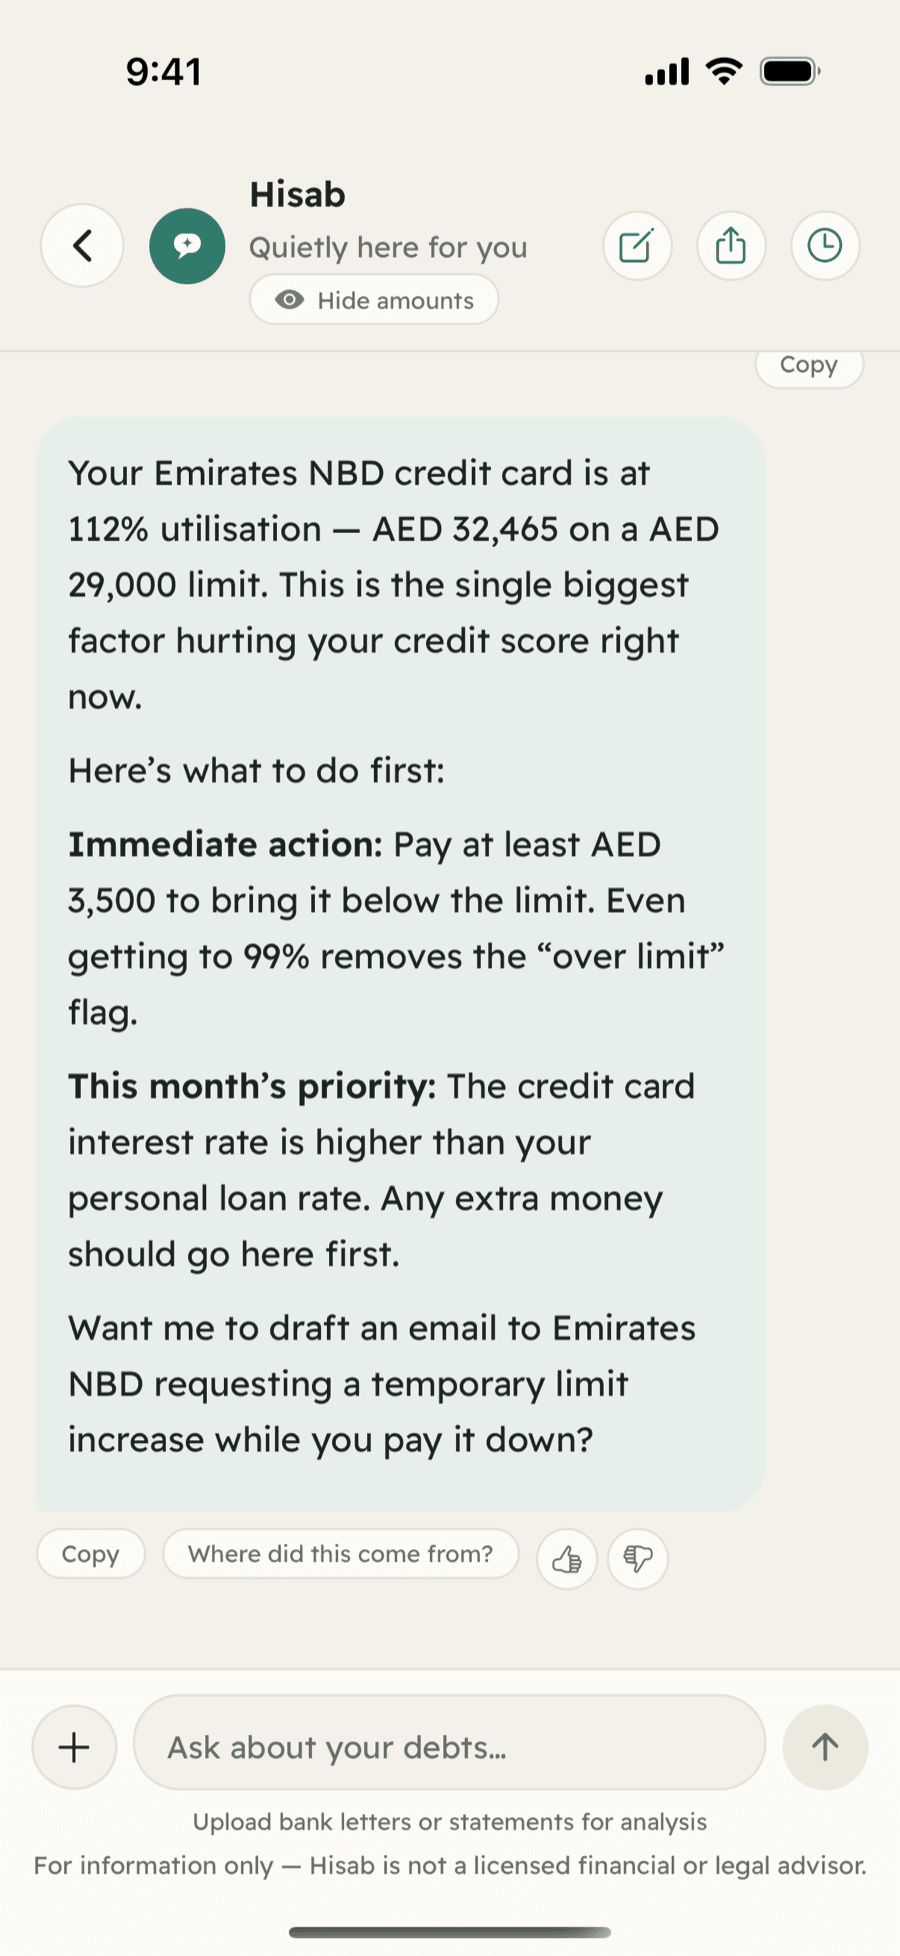
Write to your bank in 30 seconds.
Choose the bank and the situation. Hisab drafts a calm, professional email in your language. You read it, change what you like, and send it from your own account.
05
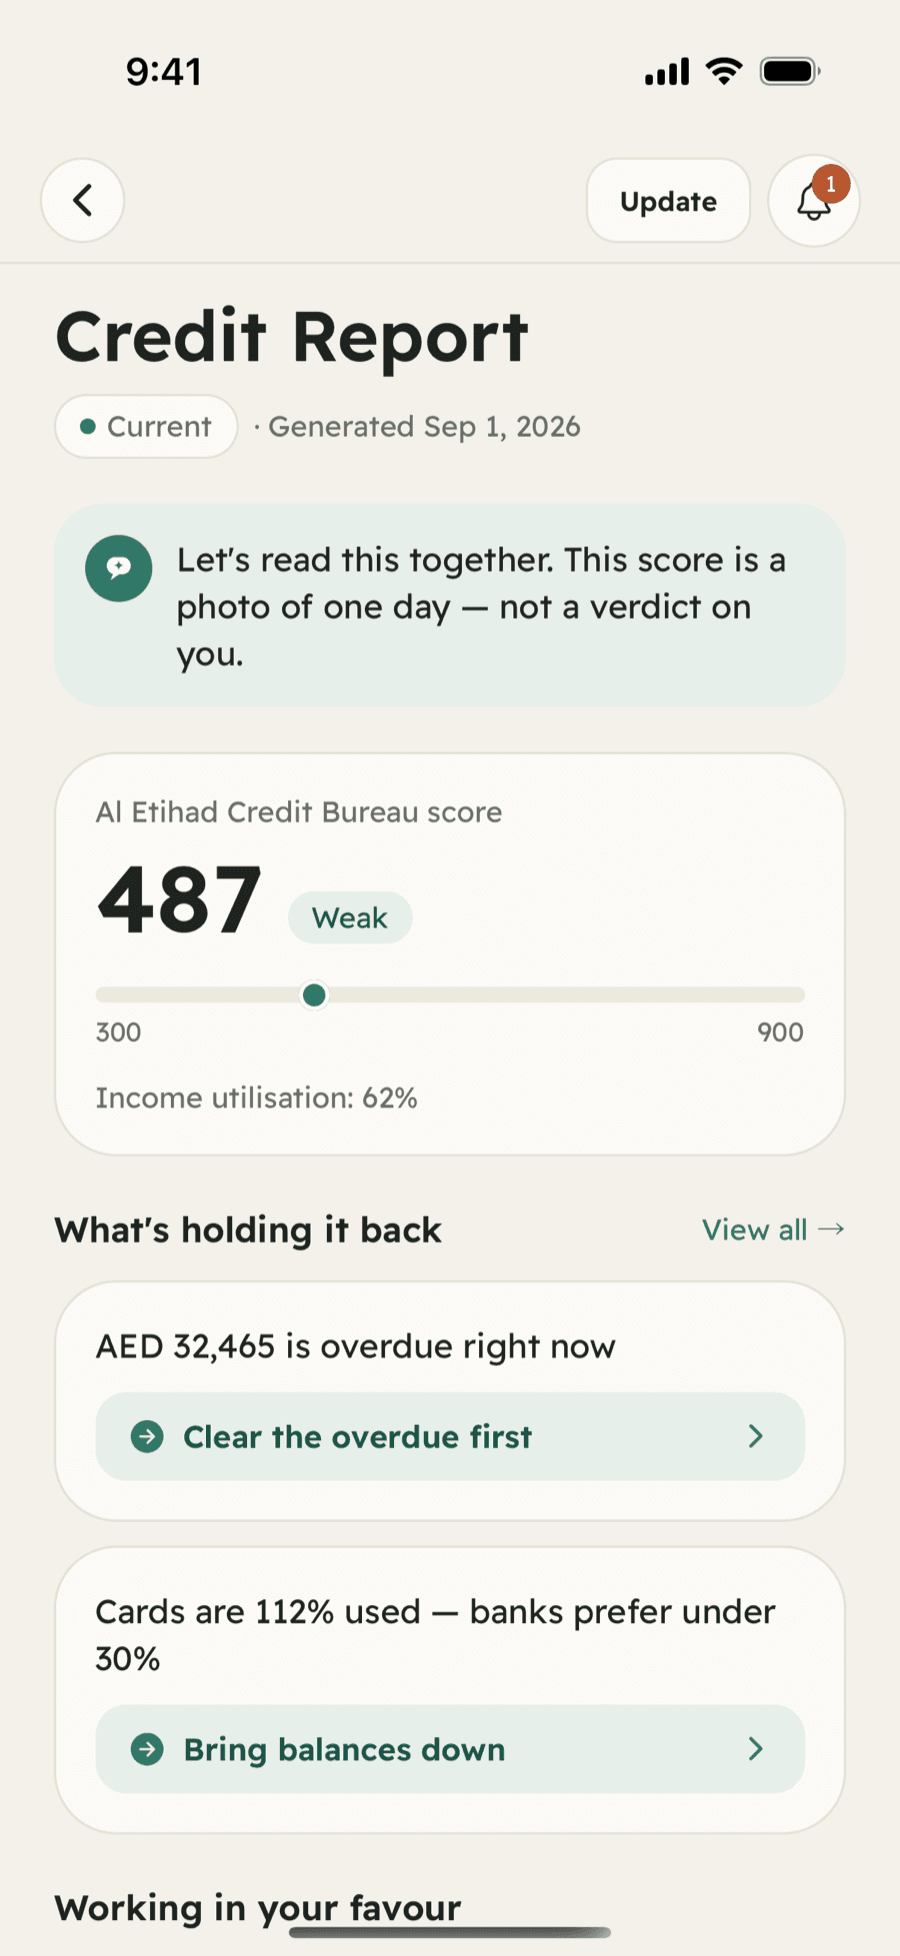
Your AECB report, decoded.
Import the official report and Hisab reads it back to you: what is holding the score back, what is already working for you, and what to do first.
On this pace
Debt-free by February 2029
0% cleared · AED 115,459 left across 3 debts
01
Every debt in one calm place.
Cards, loans, BNPL, rent, money owed to a friend. One running total, and one date you are working towards.
On this pace
Debt-free by February 2029
0% cleared · AED 115,459 left across 3 debts
02
See where your money went.
Share a bank or card statement and Hisab sorts every payment into categories for you: groceries, delivery apps, bills, buy now pay later. No typing, and it stays on your phone.
Everyday spending · August 2026
AED 4,329
Groceries25%AED 1,072
Bills16%AED 711
Shopping14%AED 608
03
Know what to pay first, and why.
Hisab ranks by pressure, not by size: legal notices first, overdue next, then the highest interest. It gives you the reason every time.
Emirates NBD Credit Card
Overdue with strong Etihad Credit Bureau impact
04
Write to your bank in 30 seconds.
Choose the bank and the situation. Hisab drafts a calm, professional email in your language. You read it, change what you like, and send it from your own account.
Subject
Request for a temporary payment arrangement
05
Your AECB report, decoded.
Import the official report and Hisab reads it back to you: what is holding the score back, what is already working for you, and what to do first.
Al Etihad Credit Bureau score
487
What’s holding it back
Clear the overdue first
Working in your favour
No accounts in default
Hisab Debt
What the app does, in four parts.
Organise what you owe. Know what to pay first. Track every payment. Write negotiation emails to your banks.
Add everything you owe
Upload your bank letters or type manually. Hisab uses AI extraction to pull out the key numbers, then keeps your saved debt plan on your phone.
See what matters most
Hisab ranks your debts by who is pressuring hardest: legal notices first, overdue second, high interest third. Not a list, a plan.
Track your payments
Set reminders. Record payments. Watch what you owe come down as you make progress. Your debt records stay on your phone.
Write to your bank
Choose your bank and situation, and Hisab drafts a professional negotiation email in your language. Deferment requests, instalment plans, hardship notifications.
Privacy
Your records live on your phone. Not with us.
Three things that are true today and will stay true.
Records stay on your phone
Debt records, salary details, and plans stay on your phone by default
AI sees only what a question needs
AI features securely send only what is needed for the task
Delete everything in one tap
No account, no email, no phone number — ever
FAQ
Questions UAE expats ask us
Is Hisab free to use?
Yes. Hisab is free to download and use, with no account required to get started. There are no ads, and we don't sell your data.
Do I need to connect my bank account?
No. You add your debts manually or scan bank letters and statements. Hisab never connects to your bank or asks for your online-banking login.
Is my financial data private?
Your debts and documents are stored on your phone, and no account is required to start. AI features send the details needed to answer your question to Google's AI to process; nothing is kept on Hisab's servers.
Will my bank know I use Hisab?
No. Hisab never connects to your bank, never asks for online-banking logins, and never contacts anyone on your behalf. You add your debts yourself, and any email it drafts is sent by you, from your own address, only if you choose to.
Can Hisab remove a travel ban or a police case?
No app can. A travel ban or case is a legal matter between you, the creditor and the court. Hisab helps you understand exactly where you stand, what usually happens next, and what to write to the bank — so you act early instead of guessing.
What happens if I lose my phone?
Your records live only on that phone, so a new phone starts fresh. There is no cloud copy of your debts today. If you want a copy, export your plan as a PDF from the app and keep it somewhere safe.
What is AECB, and can Hisab help with it?
The Al Etihad Credit Bureau (AECB) is the UAE's official credit bureau. Hisab reads your AECB report and shows what is hurting your score and what to do next.
Can the AI assistant contact my bank for me?
It drafts negotiation and hardship emails in English or Arabic for you to review and send yourself. Hisab never contacts anyone on your behalf without you.
Will my bank actually agree to a payment arrangement?
Usually the bank will work with you, but it is never guaranteed. Banks decide case by case, and a bank would rather be paid slowly than not at all. What they offer depends on the kind of debt, and it may not be exactly what you asked for: ask for a month without interest on an over-limit credit card, and the bank may instead turn the balance into a fixed instalment plan over a few months.
What can I ask my bank for if I can't keep up?
The usual options are turning a credit card balance into a fixed monthly instalment plan, a payment holiday that pauses loan payments for a short time, restructuring a loan over a longer term so each instalment is smaller, or combining several debts into one loan with a single monthly payment. Interest or profit can still build up during a payment holiday, so ask what it will cost before you agree.
What if the bank says no, offers something different, or doesn't reply?
A different offer is normal. Treat it as the start of the conversation: reply with what you can realistically pay each month, and get the final terms in writing before you agree to anything. If there is no reply, follow up by phone or at a branch. If you believe the bank has treated you unfairly and its own complaints process does not resolve it, you can escalate to Sanadak, the UAE's banking ombudsman, free of charge.
Should I contact my bank before or after I miss a payment?
Before, if you can. While your account is up to date you have the most options, and you avoid late fees and a missed payment on your credit report. If you have already missed one, write anyway: the sooner the bank hears from you, the more room there is to agree a plan.
Will a payment arrangement hurt my credit score?
An arrangement the bank formally agrees usually should not be reported as a missed payment, so it should not damage your score the way a default would. Do not assume, though. Before you agree, ask the bank in writing how the arrangement will be reported to the Al Etihad Credit Bureau (AECB).
Does Hisab work in Arabic, Hindi, and Urdu?
Yes. The entire app is available in English, Arabic, Hindi, and Urdu, with full right-to-left layout for Arabic and Urdu.
What does “hisab” mean, and why is the app called that?
Hisab (حساب, also written hisaab) is the word for accounts, calculation and reckoning in Arabic, Hindi and Urdu — “hisab lagana” is to work something out, “hisab dena” is to give an account. Hisab the app is a free, private debt app for UAE residents that does exactly that: it works out what you owe, what to pay first, and the day you are debt-free.
Download Hisab Debt Free →
Free. No account. Your numbers stay on your phone.
Download Free, No Account Needed